A customer says they will make a bank transfer once they get home. Three days later, the job is complete, the invoice is still open and somebody in the office is sending another reminder. When you send payment requests by text, you give the customer a clear, secure action to take while the conversation is still active - rather than relying on them to type in bank details, enter a reference correctly and remember to pay later.
For businesses collecting deposits, stage payments or invoices of £250 and above, this can make a material difference to cash flow and admin. A well-presented payment request turns an informal promise to transfer money into a traceable payment journey.
What does it mean to send payment requests by text?
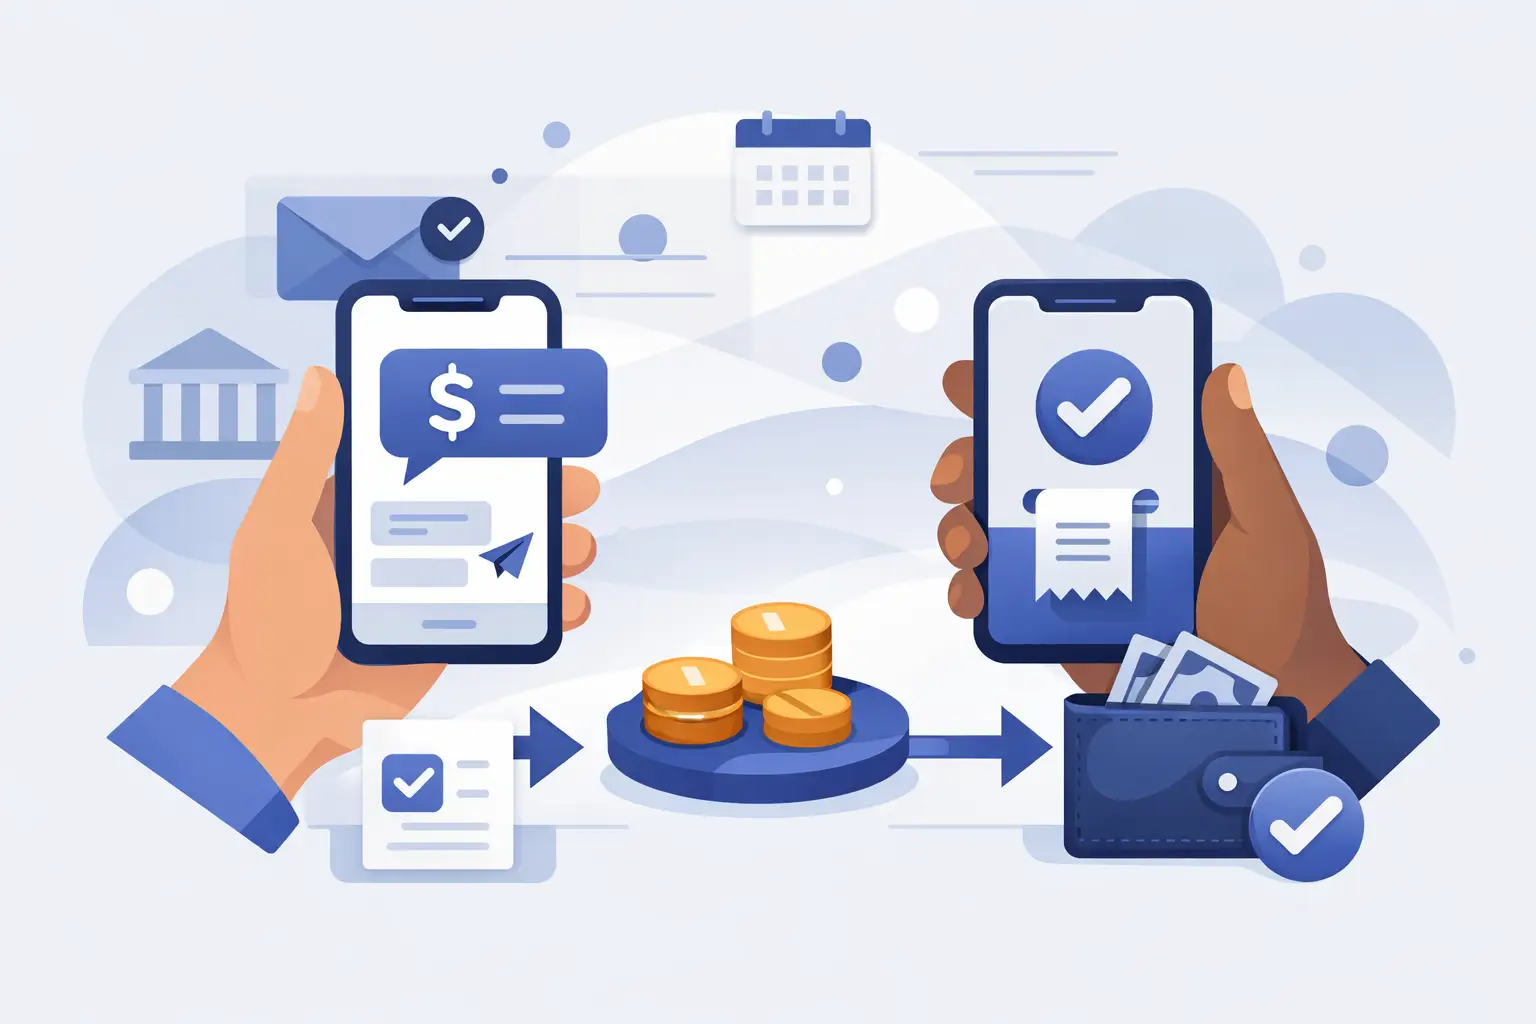
Sending a payment request by text means sharing an SMS message containing a secure payment link. The link takes the customer to a hosted payment page showing the amount due, who they are paying and the payment reference. They then choose their bank, approve the payment through their own banking app or online banking, and receive the usual bank authorisation checks.
This is not the same as texting customers your sort code and account number. Manual bank details leave the customer to enter the amount and reference themselves, which creates room for delay and error. A payment request sets those details in advance, so the customer can review and approve rather than start from scratch.
For a kitchen installer collecting a £2,000 deposit, or a garage waiting for payment after a repair, the practical benefit is simple: payment can be requested at the point the work is agreed or handed over. There is no need to take card details over the phone or wait for a customer to find a banking app later.
Why text payment requests work for larger payments
SMS is useful because it is direct. Customers tend to see a text quickly, and it sits alongside the calls and messages already used to arrange a quote, booking or collection. WhatsApp and email can be equally useful in the right situation, but text is often a reliable option when you need a prompt response without adding another phone call.
For higher-value payments, the customer experience matters as much as speed. A vague message asking someone to transfer money can feel informal, particularly if it follows a major home-improvement job or a costly vehicle repair. A branded payment page with a defined amount and clear reference gives the request more structure. It reassures the customer that they are paying the right business, for the right purpose.
The economics can also be more predictable than percentage-based card processing. If your business regularly takes substantial individual payments, a fixed per-payment charge can be easier to account for than watching the cost rise with every larger transaction. It will not suit every payment type. For very small, frequent sales, your existing card setup may still be the most practical route. But deposits, final balances and milestone invoices are a different proposition.
How to send payment requests by text in four steps
The process should be simple enough to use between site visits, appointments or customer handovers.
- Create the request. Enter the customer’s name, the amount due and a useful reference, such as “Bathroom deposit - Smith” or “Invoice 1042”. Check the amount before sending it.
- Choose SMS as the delivery method. Add the customer’s mobile number and send the request. If you have been discussing the payment on WhatsApp or by email, you may prefer to share the same request there instead.
- The customer approves through their bank. They open the payment link, select their bank and are directed to their own banking app or online banking to authorise the payment. They use their normal bank security process.
- Track the outcome and send confirmation. Your payment platform shows whether the request has been sent, viewed, paid or still needs attention. Once authorised, you can provide a confirmation or receipt and update the job or invoice record.
The payment itself moves directly between bank accounts. The request platform does not need access to the customer’s bank login details, and the customer should never share those details with your business.
Make the request feel clear, not pushy
The best text message is short, specific and expected. Tell the customer what the payment is for, state the amount where appropriate, and explain that the link will take them to a secure bank payment page. If possible, send it immediately after agreeing the deposit or completing the work.
For example: “Thanks for confirming your boiler installation. Your £500 deposit request has been sent by text. Please use the secure link to approve payment through your banking app.”
Avoid sending a link without context. Customers are rightly cautious about unexpected payment messages, especially when the amount is significant. A quick call, a written quote or a WhatsApp message confirming that the request is coming makes a genuine request easier to recognise.
It also helps to use meaningful references. “Payment request” is less useful than “Driveway balance - 14 June” when a customer is checking their bank transaction later. Good references reduce queries for both the customer and your accounts team.
Use reminders without creating awkward chasing
Not every unpaid request means a customer is refusing to pay. They may be at work, need to move money between accounts or simply have overlooked the message. A polite reminder is more effective when it includes the original context and lets them complete payment in a few taps.
Set a sensible timing based on the job. A deposit due before materials are ordered may need a reminder the same day. A final invoice for commercial work may have agreed payment terms and require a different approach. The point is not to automate pressure. It is to make following up consistent, recorded and easy to act on.
A status view is valuable here. Instead of searching message threads or asking whether somebody has checked the bank account, you can see which requests are outstanding and which have been paid. That gives the office team a cleaner handover from sales to delivery to accounts.
Security questions customers may ask
Customers may be unfamiliar with open-banking payments, so use plain answers. They approve the transaction in their own bank app or online banking using the security checks their bank already requires. Your business does not see or store their banking password, PIN or login credentials.
Regulated payment initiation infrastructure sits behind this process. With Kube Pay, payment initiation is provided by Yapily Connect Ltd, while Kube Finance Limited provides the merchant-facing payment-request platform. In practical terms, that means the customer is not being asked to trust a link with their bank details. They are confirming a payment through their own bank’s established authorisation process.
As with any payment method, customers should check the business name, amount and reference before approving. Your role is to make that information clear from the first request.
Build payment requests into the way you already work
Text payment requests are most useful when they become part of a repeatable process, not an emergency fix for overdue invoices. A roofer might send a deposit request when the customer accepts the quote, a stage-payment request before the next phase begins and a final balance request at sign-off. A clinic may send a request after confirming an appointment package. A professional-services firm may issue one alongside an invoice for work already approved.
Keep the same conventions every time: clear references, the correct customer contact, prompt confirmation and a record that can be exported for reconciliation. If several people raise requests, consistent branding and permissions help customers receive the same professional experience regardless of who sends it.
There will still be occasions when a customer prefers another payment method, and flexibility matters. But when a customer is ready to pay by bank transfer, do not make them do the administrative work. Send a defined request, let them authorise it securely and keep a clear record of what happened. That is a more professional way to collect the money your business has earned.