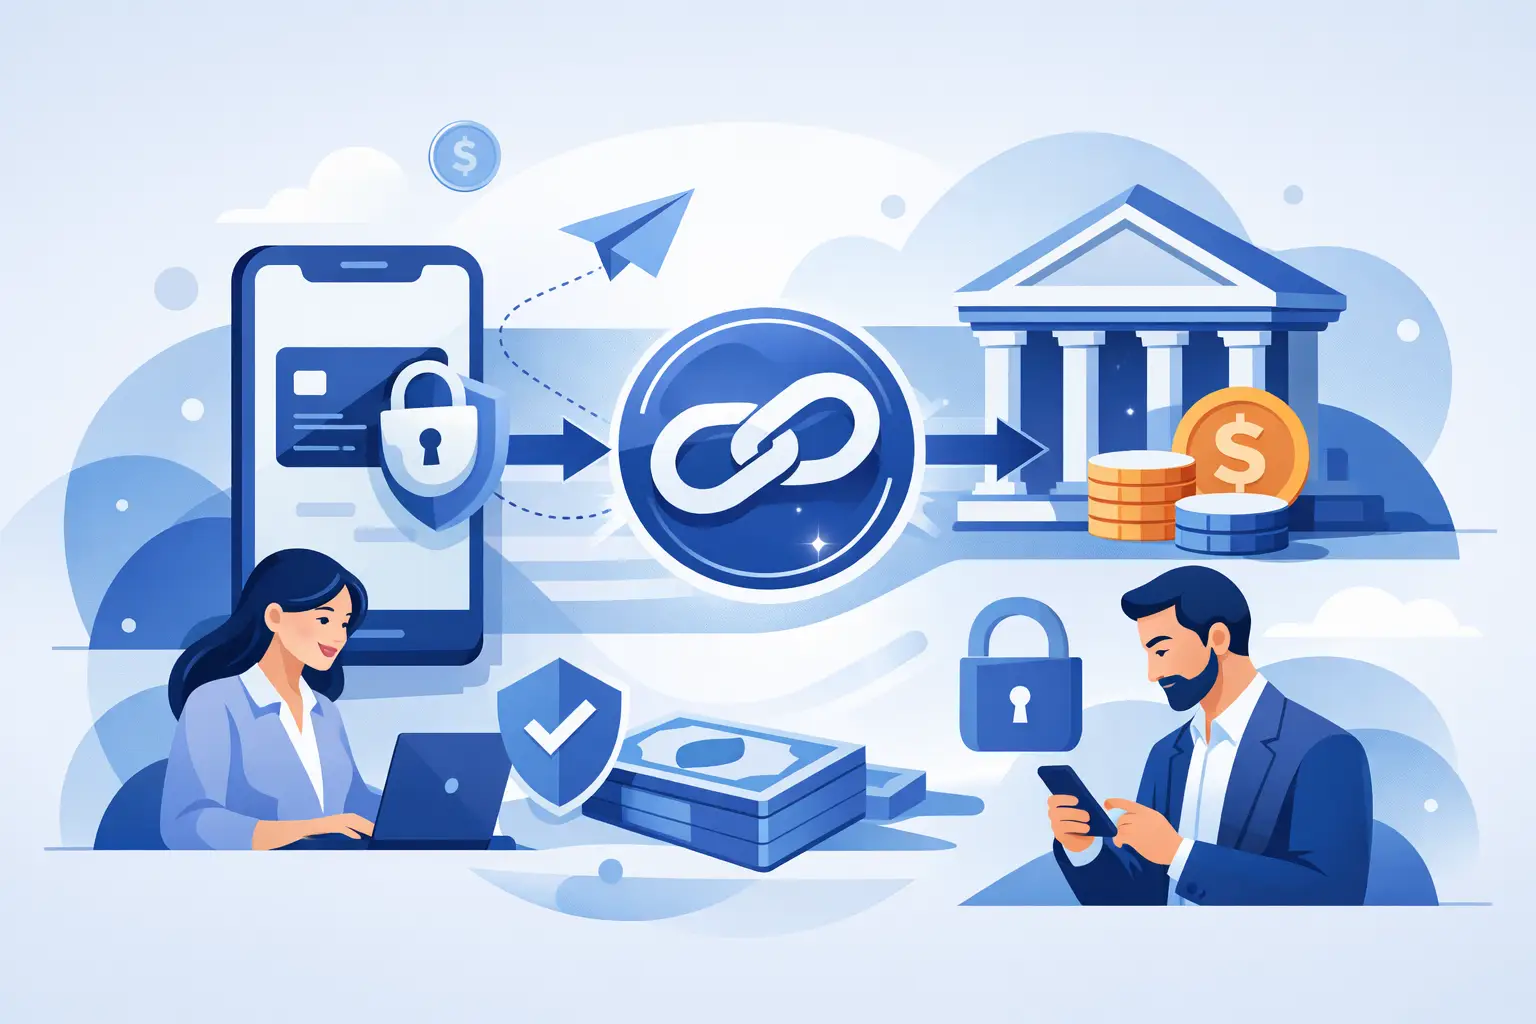
A £2,500 kitchen deposit should not depend on a customer finding your sort code, typing a reference correctly and remembering to send a screenshot. A secure bank transfer link gives them a clearer route: they receive a payment request for the exact amount, approve it in their own banking app and you receive a status update when it has been authorised.
For businesses collecting deposits, stage payments and invoices, that changes bank transfer from an informal process into a controlled payment journey. It can reduce the time spent chasing payment, prevent avoidable reference errors and give customers a professional way to pay without handing over card details.
What is a secure bank transfer link?
A secure bank transfer link is a digital payment request that allows a customer to make a bank payment through open banking. Rather than asking them to manually enter your bank details, you create a request with the amount and payment reference already set. You can then send it by WhatsApp, SMS, email or display it as a QR code.
When the customer opens the link, they choose their bank and are taken into a secure authorisation journey. They approve the payment using the security they already use for their bank account, such as their banking app, passcode or biometric check. The payment moves directly from their bank account to yours.
The key distinction is that the customer is not sharing their online banking login details with your business. They authenticate with their own bank. The payment request simply presents the correct payee, amount and reference, then uses regulated open-banking infrastructure to initiate the payment once the customer has approved it.
Why manual bank transfers create avoidable work
A standard bank transfer can look free and simple until you account for what happens around it. A customer may say they will pay later, use an old set of bank details, send the wrong amount or leave a vague reference. Your office then has to check the account, match the payment to a job and send reminders.
That friction is particularly costly when the payment is needed before materials are ordered, work begins or a vehicle is released. The issue is rarely the ability to transfer money. It is the lack of a clear, trackable request that tells the customer exactly what to do and tells your team where the payment stands.
A secure bank transfer link gives the request a defined amount and reference from the outset. It also gives the customer a prompt, professional payment experience on the channel they already use. For a roofing contractor or garage, sending a request by text while the customer is still engaged can be far more effective than sending bank details and hoping payment arrives later.
How the payment journey works
The process should be straightforward enough to use at the end of a site visit, after an invoice is agreed or when a deposit is due.
First, create a payment request with the customer name, amount and job or invoice reference. Next, choose how to send it. WhatsApp can work well for quick customer conversations, SMS is useful when a customer is away from their email, and email provides a more formal record. A QR code can be practical at a showroom, reception desk or on-site appointment.
The customer opens the request and selects their bank. They are then directed to authorise the payment through their own bank's secure process. Once they approve it, you can see the payment status and send a confirmation or receipt.
With Kube Pay, this approach is built for higher-value collections, including deposits and milestone payments over £250. The request, reminder, confirmation and reporting process is designed to give operational teams a clearer record than an unstructured bank transfer conversation.
What makes a payment link genuinely secure?
Security is not just a badge on a checkout page. It is about making it easy for a genuine customer to recognise the request, while limiting the opportunity for errors or fraud.
The customer approves in their own bank app
A legitimate open-banking payment journey requires the customer to authenticate with their bank, not with your business. Your business should never ask a customer to send their online banking password, full security code or banking-app credentials over message or email.
Because approval happens through the bank's own security controls, the customer remains in control. They can review the amount and payee before confirming the payment.
The amount and reference are pre-set
Manual transfers rely on customers copying details accurately. A secure request presents the amount you asked for and a clear reference that ties the payment to the customer, invoice or job. This reduces underpayments, overpayments and the administrative puzzle of identifying who has paid.
It also supports better communication. A customer paying a £750 boiler deposit can see exactly what the request relates to, rather than receiving a bare account number in a text message.
Regulated payment initiation sits behind the process
Open-banking payment initiation is a regulated activity. A merchant payment platform can provide the request, checkout and tracking experience, while an authorised payment initiation provider supplies the regulated infrastructure that connects to participating banks.
For a business owner, the practical point is simple: choose a provider that explains the payment journey clearly and is transparent about how payments are initiated. Avoid systems that are vague about where customers are taken to approve a payment or that ask customers to share sensitive banking information outside their bank's normal process.
Checks to make before you send a link
A payment link is most effective when the customer immediately recognises it. Use your business name consistently, include a meaningful reference and explain what the payment is for in the message that accompanies it.
Before sending a request, check the amount, the customer contact details and the reference. If it is a stage payment, say so plainly. For example: “Your payment request for the second conservatory installation stage is attached. Once approved, we can schedule the fitting team.” That is clearer and more reassuring than “Please pay ASAP”.
You should also set an internal process for expired, cancelled or unpaid requests. A polite reminder after an agreed period is better than repeatedly checking the bank account or asking the customer to confirm they have paid. Status tracking helps your team distinguish between a payment that is awaiting customer approval and one that needs a follow-up call.
When a bank transfer link is a better fit than cards
Cards remain useful for many transactions, especially lower-value or spontaneous purchases. But percentage-based card charges can become more noticeable as invoice values rise. If you regularly take deposits for a bathroom installation, bodywork repair, private treatment plan or consulting project, a fixed-cost Pay-by-Bank route may be easier to budget for.
The best method depends on the customer and the payment moment. Some customers will prefer a card, while others are comfortable authorising a bank payment in the app they use every day. Offering a clear bank-payment request gives you another route to collect funds without turning every larger payment into a manual transfer chase.
It also helps to separate payment collection from payment reconciliation. A hosted request can provide confirmation, receipts, reminders and reporting, while CSV exports make it easier to pass accurate records to your accounts process. That is useful when several team members take payments or when job references need to match invoices reliably.
Give customers certainty, not just bank details
The strongest payment experience is not the one with the most technical language. It is the one where a customer knows what they are paying, why they are paying it and how to approve it safely. A well-presented secure bank transfer link does exactly that, while giving your business a practical record of every request and response.
For larger jobs, that clarity can be the difference between waiting for a promised transfer and confidently moving on to the next stage of work.